Infrastructure projects frequently encounter delays and budget overruns due to unpredictable natural hazards, complicating traditional risk management and financial planning. Integrating insurance into the financial analysis of large infrastructure projects offers a powerful tool for mitigating the effects of these exogenous shocks. Quantitative Risk Analysis (QRA), a probabilistic method for forecasting project budget and timelines, can play a central role in managing such uncertainties (Danesh-Mand, 2019). However, when addressing natural hazards, indemnity insurance greatly complicates the modelling of various contingencies as it struggles with volatility in both hazard occurrence and asset vulnerability. By shifting the focus to parametric insurance and its predefined hazard triggers, a more streamlined and transformative solution can be imagined, which provides optimisation from reduced modelling complexity and enhanced financial predictability.
Aligning QRA with Catastrophe Risk Modelling
Conventional catastrophe risk models, widely adopted by insurers and reinsurers, hinge on three key elements: hazard, exposure, and vulnerability. Hazard concerns the probability and intensity of disruptive events like hurricanes, while exposure focuses on the communities or assets at risk. Vulnerability describes how the severity of potential losses scales with varying hazard intensities; it also adds a considerable amount of uncertainty to risk assessments, increasing the variability of expected costs. In a similar vein, Quantitative Risk Analysis (QRA) models are also structured around three key elements that mirror the catastrophe risk model. In QRA, hazard corresponds to the risk event itself, such as a delayed shipment or a weather event. Exposure refers to the critical project activities or milestones that are at risk from these events, while vulnerability in QRA describes how sensitive the project timeline and total expected costs are to these hazards, considering factors such as resource availability, project complexity, and risk management practices. Just as vulnerability in catastrophe risk models drives uncertainty around potential losses, in QRA, it increases the uncertainty around project delays and associated costs, making it more difficult to forecast and manage project timelines accurately. The challenge in both models is managing this uncertainty to achieve better risk predictions and more reliable outcomes.

Within a project context, natural hazards such as intense rainfall or prolonged heatwaves trigger events that complicate modelling under traditional indemnity policies. Consider a construction site experiencing severe rainfall: the resulting damage (possible vulnerabilities/ contingency pathways), which varies from drainage overload and waterlogged electrical equipment to slope instability, can create diverse and intricate contingency/ vulnerability pathways, complicating the QRA process. Additionally, indemnity insurance relies on detailed on-site assessments to determine payouts, prolonging settlements and adding further uncertainty to cost projections and schedule management.
Parametric insurance significantly reduces these complexities by minimising reliance on detailed vulnerability assessments. Instead, it ties insurance coverage directly to predefined hazard thresholds, such as specific wind speeds or rainfall volumes. Clear payout conditions established in advance simplify capital requirements and expedite financial settlements, crucial in an era of intensifying climate risks. This immediacy and predictability streamline risk modelling, making financial planning more robust and resilient for large-scale infrastructure projects.

As illustrated in Figure 2, parametric coverage narrows the range of contingency pathways in schedule cost analysis and makes it simpler to estimate potential losses. With fewer critical scenarios beyond the parametric payout threshold, modelling complexity drops significantly, offering greater control over budgeting and scheduling. This approach eliminates many of the assumptions that traditionally complicate risk assessments in large-scale projects and streamlines both cost and schedule projections.
Enhancing Predictability and Financial Planning
Parametric insurance can align seamlessly with project milestones. For example, if the critical path of a major development intersects with a seasonal cyclone period, a cyclone-indexed policy can provide near-instant liquidity when the storm hits and its intensity surpasses a set threshold. This immediate funding bypasses lengthy damage assessments, enabling rapid debris removal, remobilisation of crews, and broader supply chain adjustments. Such efficiency protects narrow profit margins and brings more predictability to multi-phase ventures. Integrating these parametric triggers into QRA further provides developers and financiers with heightened awareness of potential schedule disruptions, the likelihood of those disruptions, and the extent of liquidity available for swift recovery. By embedding these triggers into planning models, project stakeholders can more accurately allocate capital and manage resources across diverse operational phases.
Incentivising Proactive Resilience During Construction
Parametric coverage, though it simplifies payouts by focusing on hazard thresholds, introduces basis risk—the possibility that triggered payouts may not perfectly align with actual damage. The existence of basis risk works as an incentive for project teams to tackle the most sensitive vulnerability pathways and take matters into their own hands, whether through self-insurance or other proactive measures that mitigate real-world impacts. Knowing precisely which hazard levels will trigger coverage, and to what extent, enables them to allocate resources effectively, for instance by elevating critical infrastructure or reinforcing supply routes. Moreover, parametric insurance remains flexible enough to accommodate a range of triggers suited to each company’s capabilities and project specifications; an insurer might offer policies for water thresholds of two, four, or six meters. By targeting these critical stress points and customising coverage, stakeholders minimise delays, stabilise financial exposure, and ultimately lower the overall risk profile for large-scale ventures.
Real-World Example: Norco’s Post-Flood Risk Management in Lismore
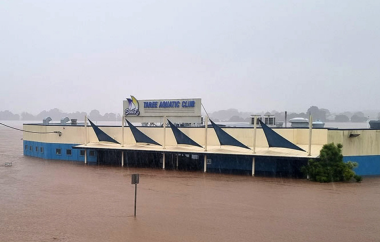
Norco’s recovery efforts after the devastating floods in February 2022 illustrate the synergy between proactive measures and parametric coverage. The historic Lismore ice cream factory, severely damaged by floodwaters exceeding previous records by over two metres, underwent an extensive $100 million rebuild. Supported by $46 million in joint funding from the Australian and New South Wales governments, the reconstruction incorporated significant flood mitigation strategies, including elevating critical infrastructure and installing submarine-style doors to protect essential equipment (Herbert, n.d.).
In alignment with these structural enhancements, as highlighted on 6th March during the 2025 Catastrophe and Reinsurance Symposium in Sydney, Norco is considering the adoption of parametric insurance policies designed to trigger payouts when floodwaters surpass predefined levels. This approach facilitates rapid financial support, bypassing the delays associated with traditional damage assessments, and ensures smoother continuity of operations. The integration of parametric coverage into Norco’s risk management strategy underscores the company’s commitment to resilience and serves as a model for other large-scale projects facing similar natural hazard risks (N.S.W Government, 2024).

Prospects and Limitations
As climate risks intensify globally, parametric insurance is likely to gain broader traction, not only among insurers but also across the engineering and project management communities. Its transparent triggers rapid payouts, and alignment with strategic planning make it a valuable instrument for those responsible for designing and delivering resilient infrastructure. As such, engineers and project managers should become familiar with how parametric policies function and how they can be integrated into risk management strategies. Continued advances in technology will further refine hazard indices, enhancing the relevance of parametric solutions in high-risk scenarios. While challenges such as scalability and basis risk remain, these can often be addressed through careful, data-driven policy design. Ultimately, parametric insurance offers both immediate liquidity and a powerful incentive for proactive resilience, making it an indispensable tool for financial risk mitigation and planning of large infrastructural projects in the face of increasingly severe natural hazards.
Role of Risk Modelling Firms
Organisations like Risk Frontiers can help insurers by providing historical and simulated event occurrences to develop robust trigger mechanisms, calibrate hazard indices, and validate data, ensuring parametric coverage aligns with regulatory requirements and broader risk reduction goals. By fine-tuning parametric triggers and reducing basis risk, they build confidence in how payouts are handled, ultimately making parametric insurance a more reliable and effective tool.
They can also collaborate with consulting engineering firms to choose appropriate hazard levels and protection measures suited to a project’s risk profile. By bridging data-driven modelling with practical construction insights, this integrated approach ensures that parametric coverage accurately reflects real-world conditions and fosters a proactive resilience culture.
Conclusion
Parametric insurance reduces the distribution of uncertainty, transitioning the focus from complex vulnerability assessments toward simpler, hazard-based triggers. When combined with proactive resilience strategies, such as Norco’s flood mitigation efforts, and by considering parametric insurance as a risk transfer mechanism in such projects, parametric coverage becomes a powerful financial and operational safeguard. Stakeholders and project managers are thus encouraged to integrate parametric insurance into infrastructure project planning to bolster resilience, stabilise finances, and ensure sustainability amid escalating climate-related risks.
References
Danesh-Mand, P. (2019). Contingency Guideline. In Risk Engineering Society (RES), Engineers Australia (2nd ed.). Engineers Australia. http://catalogue.nla.gov.au
Gem Foundation (2024). Scenario Damage Calculator. Global Earthquake Model (GEM); GEM Foundation. https://cloud-storage.globalquakemodel.org/public/wix-new-website/pdf-collections-wix/projects/bangladesh/outreach/png%20UNDRR-GEM%20Bangladesh%20-%20Technical%20Panel%20-%20Session%204%20-%20Scenarios%20and%20Risk.png
N.S.W. Government (2024). Lismore ice cream factory reopens stronger than ever. NSW Government News. https://www.nsw.gov.au/news/lismore-ice-cream-factory-reopens-stronger-than-ever
Herbert, B. (n.d.). Lismore’s Norco ice cream factory opens after $100 million rebuild from flood damage. ABC News. https://www.abc.net.au/news/rural/2023-11-24/norco-ice-cream-factory-reopens-lismore-flood/103148852